MoneyPilot : Class Action
- 4.6
- Rating
- 50.00K
- Installs
- Free
- Price
 Analysis by App-foxy
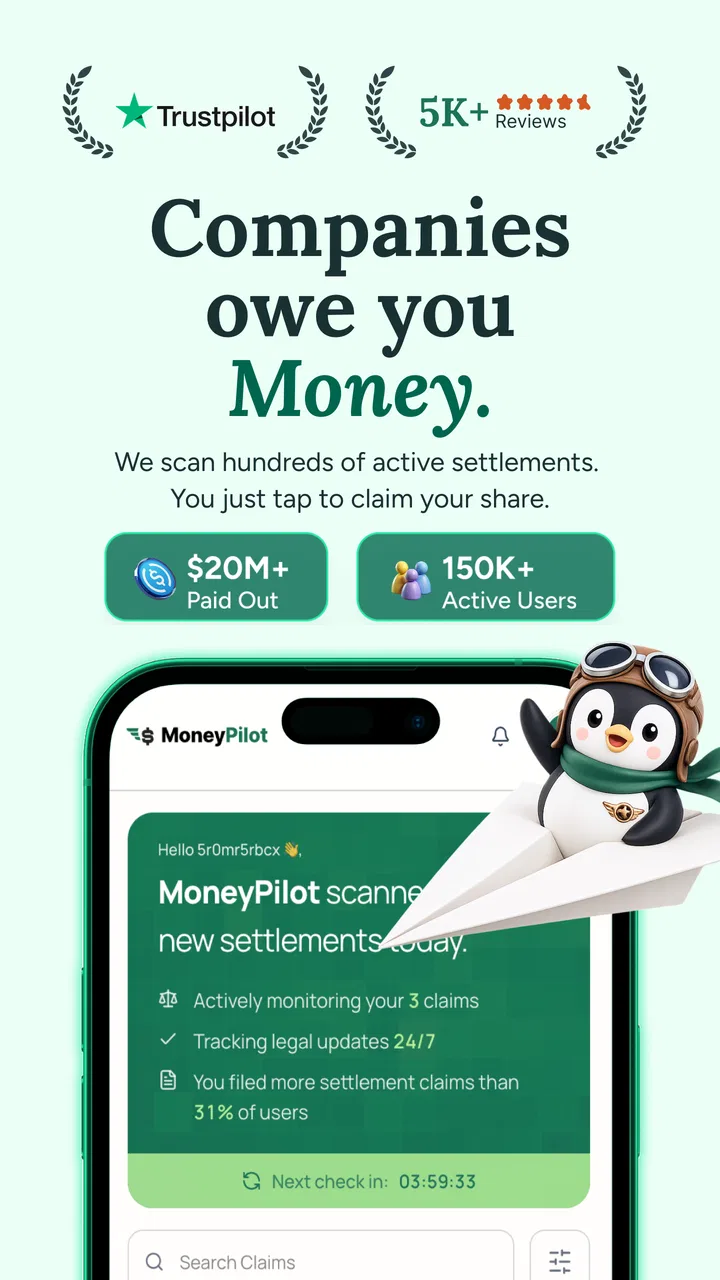
I approached MoneyPilot: Class Action as a practical finance app rather than a general money-management tool. Its focus is narrower and more unusual: helping people find and track claims, submit payout claims, and look for money connected with settlements. That makes the right question less “Can this replace my banking app?” and more “Will it help me notice and manage opportunities I would otherwise miss?”
After spending time with it, my view is that the app is most useful for people who are willing to review potential claims carefully and keep an eye on their progress. It is free to install, aimed at Everyone, and comes from Bloom Processing. The app has attracted a 4.6 average from around 2K ratings and has passed 50K installs, which suggests that its focused idea is reaching a real audience without pretending to be a full personal-finance suite.
How I would decide whether MoneyPilot fits
The first decision is about your habits. If you already follow consumer settlements, remember every service you have used, and are comfortable completing forms, this app can give that process a more convenient home. If you rarely read notices, dislike paperwork, or expect automatic money with no checking on your part, the experience may feel like extra administration.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk
View All News


I would also separate three jobs that are often confused. Finding a possible claim is one job. Checking whether you qualify is another. Submitting the claim and watching what happens afterward are separate tasks again. MoneyPilot is built around this chain, so it makes more sense than a normal budgeting app when your goal is settlement-related money rather than tracking spending or planning monthly bills.
That distinction matters because a claim is not the same thing as guaranteed income. A listing may be relevant to your history but still require eligibility details, dates, receipts, account information, or other supporting material. My best advice is to treat every opportunity as something to investigate, not as a promise. Read the conditions before submitting, save copies of anything you send, and avoid rushing simply because a deadline appears important.
A useful personal test is to ask whether you can describe the services, products, or subscriptions you have used in recent years. You do not need a perfect memory, but a rough record makes the app more valuable. Old email receipts, account histories, and payment records can help you decide whether a claim deserves attention. Without those references, it is easy either to overlook a legitimate match or to spend time on claims that do not apply.
A realistic way to use it during an ordinary week
Imagine I receive a notification or open the app during a quiet moment on the weekend. Instead of immediately submitting the first claim I see, I would scan the available opportunities and make a short list of the ones connected to services I recognize. I would then check the eligibility wording, look through old email for proof of use, and prepare the details before returning to the submission screen.
That workflow is more reliable than treating the app like a scratch card. The time-saving benefit comes from organizing the search and follow-up, not from removing the need for judgment. I would keep a simple note outside the app with the claim name, the date submitted, any confirmation reference, and the next action. That small habit is especially helpful when several claims have similar names or when a payout may take time.
Another non-obvious advantage of this approach is that it separates discovery from documentation. I can browse when I have a few minutes, then gather evidence later when I have access to old statements or inbox searches. That is less frustrating than trying to complete everything in one sitting, and it reduces the chance of submitting incomplete or inaccurate information just to finish quickly.
What the focused design does better than broad finance apps
Most finance apps are designed around spending, saving, investing, credit, or bills. They answer questions such as where your money went and how much you can afford. MoneyPilot addresses a different blind spot: money connected to past transactions or participation that may not appear in a normal account overview.
That focus is its clearest strength. A budgeting app may show a recurring charge but will not normally turn that history into a settlement-search workflow. A banking app may show the payment but not help you think about whether a related claim exists. MoneyPilot is more relevant when the money you are looking for is not part of your regular cash flow yet.
The tracking side is also important in principle. Submitting a claim is only the beginning, and people often lose confirmation emails or forget which opportunities they pursued. Keeping discovery and follow-up in the same purpose-built app can reduce that mental load. I would still keep my own record for important submissions, but having a central place to revisit the process is more practical than relying on scattered browser tabs and inbox searches.
For someone who has never handled a class-action claim before, the app’s value is not just speed. It gives the activity a recognizable structure: find, review, submit, and monitor. That sequence helps prevent a common mistake, which is assuming that finding a matching title means the process is complete.
Three habits that make the app more useful
First, I would search by personal history rather than by curiosity. Think about former subscriptions, retailers, devices, services, and purchases, then compare those memories with the opportunities shown. This produces a more manageable list and keeps the app tied to situations where I can actually judge eligibility.
Second, I would prepare a small evidence folder before submitting anything that asks for supporting details. It might contain receipts, account emails, order records, or statements already available to me. The point is not to collect unnecessary personal information; it is to avoid repeatedly hunting for the same proof and to submit only what the claim instructions genuinely request.
Third, I would review the tracking area on a schedule rather than constantly checking it. A weekly or biweekly review is more sensible than opening the app several times a day. During that review, I would look for claims needing action, compare saved notes with the current status, and remove opportunities I know are irrelevant. This turns the app into a manageable routine instead of another source of notifications.
There is also a privacy-minded trade-off here. The more personal history I use to evaluate claims, the more careful I need to be about what I upload or enter. I would read each request closely, provide only necessary information, and avoid assuming that every field is mandatory simply because it is visible. That caution is not a criticism unique to MoneyPilot; it is sensible whenever financial or identity-related details are involved.
Where other choices may fit better
I find that comparing MoneyPilot with other options comes down to how much discovery and follow-up you want in one place. If you already know which settlement you’re pursuing, checking its official instructions directly may be simpler; if you’re trying to keep possible claims from slipping past, a dedicated workflow can be more useful. That distinction helps set realistic expectations before deciding whether this app deserves a recurring spot in your routine.
When a general finance app is the better tool
If your main problem is overspending, irregular bills, debt repayment, or saving for a goal, I would choose a conventional budgeting or banking application first. MoneyPilot is not the natural place to build a monthly budget or understand your everyday cash position. Its settlement-centered purpose means it should complement those tools, not replace them.
Likewise, people who want investment research, credit monitoring, tax preparation, or detailed account aggregation should look at apps designed specifically for those jobs. Trying to force one narrow claims tool into a complete financial command center would create the wrong expectations and make the comparison unfair.
When manual searching may be preferable
Some users may prefer to search official settlement notices and submit through the relevant administrator directly. That route can feel clearer when I already know the name of a case or want to inspect the original instructions from the source. It also avoids adding another app to my routine.
The trade-off is convenience. Manual searching requires remembering where to look, checking multiple sources, and maintaining my own follow-up system. MoneyPilot is more appealing when discovery is the difficult part. If I am already organized and only need to submit one known claim, the app may offer less benefit than it would for someone trying to discover several possibilities.
I would also be cautious about choosing any tool solely because it makes a claim sound easy. The important comparison is not just the number of steps. It is whether the process helps me understand eligibility, retain confirmation details, and return to unfinished work without confusion. A simpler-looking route is not automatically better if it leaves me unsure about what I submitted.
What the app cannot solve for you
MoneyPilot can organize the search and submission process, but it cannot turn an uncertain match into a valid claim. I still need to read the terms, answer accurately, and keep realistic expectations about the outcome. That human checking is the main limitation of the category itself, and it is where impatient users may feel the most friction.
I would also avoid using it as a reason to submit every possible claim. Over-submitting can make my records messy and may encourage careless answers. A smaller set of well-supported submissions is a better workflow than a long list based only on familiar company names or vague memories.
Understanding the cost before committing
The app is free, which makes trying the basic experience relatively easy. It does include optional in-app purchases ranging from about four dollars to around one hundred dollars per item. Because that range is broad, I would pay close attention to the purchase screen and understand exactly what each optional item provides before confirming anything.
My own rule would be simple: do not spend money merely because a possible payout sounds attractive. First determine whether the claim is relevant, whether the submission is complete, and whether the optional purchase offers a clear benefit to the task I am actually trying to finish. A free starting point is useful, but it should not encourage impulse spending.
This is also where the cost of switching matters. Moving from manual searches to MoneyPilot may save organization time, but it introduces a new routine: learning the interface, reviewing opportunities, and deciding how to record submissions. Moving from MoneyPilot back to manual tracking is possible, but I would export or copy my notes first so that confirmation details and follow-up dates do not disappear into memory.
The current release is version 1.0.55 and supports Android 7.0 or later. That gives the app a broad compatibility range for Android users, although I would still keep the application updated and use a device I trust when entering sensitive information. The age classification is Everyone, but the subject matter is more relevant to adults who have transaction histories and can evaluate financial forms independently.
Who should use it and who should skip it
I would recommend giving it a trial if you have used many consumer services, tend to lose track of settlement notices, or want one place to review possible claims and their progress. It is particularly suitable for methodical users who are happy to verify details and maintain a small record of what they submit.
I would skip it if you are looking for a spending tracker, a bank replacement, or an instant payout service. I would also hesitate if you dislike reading eligibility language or cannot comfortably distinguish a possible opportunity from a confirmed payment. In those cases, a standard finance app or direct official research may be a better match.
Families may find the Everyone rating reassuring, but I would still supervise any process involving personal, purchase, or payment information. The rating describes general suitability; it does not remove the need for an adult to review forms and decide what information is appropriate to enter.
My recommendation after weighing the trade-offs
MoneyPilot: Class Action is worth trying when your missing financial habit is claim discovery and follow-up. I like that it concentrates on a task ordinary banking and budgeting tools usually ignore. The combination of finding opportunities, submitting claims, and tracking progress gives the process a useful shape, especially for people who would otherwise depend on scattered searches and forgotten emails.
My recommendation comes with a clear condition: use it as an organizer, not as a promise of easy money. Check every eligibility requirement, keep your own confirmation notes, protect personal information, and examine optional purchases before paying. Those habits matter more than simply installing the app.
Bloom Processing has made a focused finance app rather than an all-purpose money manager, and that narrowness is both the reason to choose it and the reason to avoid it. If settlement claims are relevant to your past purchases or services, the free entry point and dedicated workflow make sense. If your financial goals involve budgeting, debt, investing, or everyday banking, choose a specialist tool for those needs and treat this one only as a companion.
In short, I would keep MoneyPilot in my toolkit for occasional, organized claim research. I would not make it the center of my financial life, and I would not submit anything without reading the conditions. Used with that level of care, it can turn an easy-to-forget task into a repeatable process without pretending that every listed opportunity will lead to a payout.
FAQs for MoneyPilot : Class Action
01What is MoneyPilot: Class Action?
MoneyPilot: Class Action is an app designed to help users discover and review potential class action settlements and consumer compensation opportunities. It may provide information about eligibility, claim deadlines, settlement details, and required documentation. Before relying on any listing, users should carefully read the official settlement notice and confirm that the information is current and relevant to their situation.
02How does MoneyPilot: Class Action help me find settlements?
The app organizes available class action information so users can browse opportunities that may apply to products, services, subscriptions, or purchases they have used. Listings can typically include a summary of the case, estimated eligibility requirements, filing deadlines, and instructions for submitting a claim. The app should be treated as an informational tool rather than a guarantee that a claim will be accepted or paid.
03Is MoneyPilot: Class Action free to use?
Users should check the app’s current store listing and in-app terms to confirm whether MoneyPilot: Class Action is completely free or includes optional purchases, subscriptions, or other charges. Even when browsing is free, some features may require payment. Review the pricing details, renewal conditions, and cancellation instructions before entering payment information or activating a premium feature.
04Can MoneyPilot: Class Action guarantee that I will receive money?
No app can guarantee that a user will receive compensation from a class action settlement. Eligibility depends on the official settlement rules, the accuracy of the information submitted, available funds, and the claims administrator’s review. MoneyPilot may help users locate opportunities and understand the process, but it does not replace official notices, legal advice, or confirmation from the settlement administrator.
05What information should I provide when submitting a claim?
The information required depends on the individual settlement. A claim may request contact details, proof of purchase, account records, transaction dates, receipts, or other documentation. Only provide information that is genuinely required through a trusted and verified claims process. Before submitting sensitive personal or financial data, confirm the settlement’s official website, privacy policy, deadline, and claims administrator.
Pros
- Simple interface makes case and claim information easy to browse.
- Helps users discover potential class action settlements in one place.
- Claim updates can reduce the need to search individual court websites.
- Useful for tracking important filing deadlines and settlement changes.
- Free access makes the app easy to try without an upfront cost.
Cons
- Eligibility checks may still require careful review of official settlement terms.
- Settlement listings may not include every active class action.
- Notifications can become distracting if many cases are being tracked.
- Claim processing times depend on administrators
- not the app itself.
- Users should review privacy terms before sharing personal claim details.

MoneyPilot : Class Action
Gallery